
Blogs
PW Consulting: Worldwide Wheel Balancer With Touchscreen Market Hits USD 391.0 Million in 2025, Poised for Further Growth
By pmarketresearch, 2026-08-12
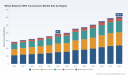
Worldwide Wheel Balancer With Touchscreen Market — Strategic Outlook for 2026: Why C-Suites and Product Leaders Need PW Consulting’s New Report
Executive summary
PW Consulting’s latest market research report on the Worldwide Wheel Balancer With Touchscreen Market (base year 2025, historical 2020–2025, forecast 2026–2032) delivers a pragmatic, decision-focused view for executives planning capital allocation, product roadmaps, and M&A activity in 2026. Our analysis finds the market at a clear inflection point: after robust recovery through 2020–2025, the installed-base upgrade cycle and rising demand for digitally enabled shop equipment will sustain growth through the forecast period at a compounded annual growth rate (CAGR) of approximately 6.55%.
Worldwide Thermal Conductive Sheet Market
Why this matters for 2026 strategy
-
Market momentum entering 2026 supports confident investment but requires selective prioritization. With the global market size measured at the 2025 base year and modeled through 2032, players must choose between competing near-term returns and long-term platform plays (connectivity, diagnostics, and automation).
Worldwide Flotation Cell Market -
Touchscreen-enabled balancing equipment has migrated from “nice-to-have” to a productivity and diagnostic hub in professional workshops. Decisions in product development, channel incentives, and aftermarket service investments in 2026 will determine who captures the high-value upgrade cycle.
Digital Pathology Image Analysis Software for Clinical Market -
Supply-chain and material considerations—particularly steel and electronic components—introduce cost and lead-time variability that will affect 2026 procurement strategies and pricing policies.
Market trajectory and sizing: what the numbers mean
Our bottom-up model synthesizes equipment shipments, replacement cycles, average selling prices, and aftermarket demand to project the market through 2032. The 2025 market midpoint is a practical decision benchmark: it quantifies the absolute scale of opportunity while the 6.55% CAGR provides the growth tempo buyers and investors should expect. Together these metrics help stretch internal business cases beyond anecdote to a defensible financial plan for 2026 investments — whether funding an R&D sprint, expanding distribution, or underwriting a tuck-in acquisition.
Key market dynamics shaping 2026 choices
-
Technology convergence: Touchscreen interfaces have become table stakes; value differentiation now comes from embedded diagnostics, 3D imaging, laser-guided workflows, and seamless connectivity with dealer/shop management systems. OEMs and independent manufacturers are converging on platform-level features that increase workshop throughput and service ticket depth.
-
Automation spectrum: The market is bifurcated between high-throughput fully automatic systems and flexible semi-automatic solutions. Each segment maps to distinct buyer economics — from large multi-bay tire shops and vehicle manufacturers to smaller independent service centers — and therefore requires different go-to-market plays.
-
Raw material and component exposure: Steel, sensors, motors, and electronic subsystems are core inputs. Our sector analysis indicates procurement volatility and concentrated component supply chains; contract manufacturers and OEMs should embed scenario-based sourcing strategies into 2026 operating plans.
-
Regulatory and sustainability pressures: Environmental rules are accelerating the shift to recyclable weighting materials. Zinc-based balancing weights are gaining share because of recyclability, despite carrying a price premium versus legacy alternatives — a factor that intersects with product positioning and customer education requirements for 2026.
-
Aftermarket expansion: Rising vehicle parc and ongoing aftermarket demand are durable tailwinds. However, the revenue mix is evolving: sales of diagnostic-capable balancers, recurring software subscriptions, and service contracts are becoming material contributors to lifetime value.
Competitive landscape — patterns, not playbooks
The vendor ecosystem is populated by long-established workshop-equipment manufacturers and fast-moving innovators. Our qualitative and quantitative assessment highlights three practical takeaways for 2026 planning:
-
Differentiation through integration: Firms that package touchscreen hardware with advanced diagnostic suites and automated workflows create stickier customer relationships. Leaders are layering features such as laser weight placement, 3D/2D imaging, and guided user interfaces to reduce service time and up-sell consumables and diagnostics.
-
Margin pressure and premiumization: Vendors targeting high-volume professional shops are investing in direct drive architectures and diagnostic-capable models to justify premium pricing. Conversely, semi-automatic, cost-efficient platforms remain essential to capture smaller service centers where capital budgets are constrained.
-
Service and channel economics: Companies that strengthen dealer training, remote diagnostic support, and spare parts logistics gain a competitive edge. Aftermarket service contracts are fast becoming a principal lever to improve gross margins and customer retention.
Our competitor profiles evaluate product portfolios, go-to-market footprints, and innovation cadence across the vendor set. The analysis examines strengths such as specialized diagnostic offerings, touchscreen ergonomics, and digital ecosystems, and highlights where gaps exist for entrants and incumbents alike.
What PW Consulting’s report contains — practical assets for 2026 execution
The report is designed as an operational toolkit for executives, deploying robust methodology and deliverables you can act on immediately. Key components include:
-
Market sizing and near-term forecasts (base year 2025; forecast 2026–2032) with scenario sensitivity to macro and commodity shocks.
-
Competitive benchmarking and capability maps that assess product features (touchscreen size, diagnostics, automation), channel strength, and service ecosystems.
-
Technology and product roadmaps: an innovations matrix that ranks features by adoption risk, implementation complexity, and ROI potential.
-
Supply-chain risk register and mitigation playbook, with stress-tested sourcing scenarios for steel, motors, and electronic subsystems.
-
Commercial playbooks for three buyer segments (high-volume professional shops, independent service centers, and OEMs) that translate market signals into pricing, bundling, and distribution tactics.
-
M&A watchlist and target scoring framework—prioritized using strategic fit, product synergies, and integration risk metrics.
-
Financial models and an ROI calculator to evaluate product investment, channel expansion, and aftersales subscription strategies under multiple market-growth assumptions.
Recent developments and implications
Notable vendor-level activity reinforces the market themes we identify. For example, a recent product launch from a U.S. equipment manufacturer introduced a diagnostic-heavy balancer targeted at high-volume shops, illustrating the competitive premium being placed on embedded diagnostics and workflow efficiency. Such moves underscore the importance of aligning 2026 product roadmaps with shop productivity metrics and software-enabled service monetization.
Strategic recommendations for 2026 (actionable priorities)
-
Prioritize modular architecture: Build touchscreen platforms with modular software and sensor interfaces to accelerate feature rollouts and reduce upgrade friction for customers.
-
Invest in aftermarket economics: Bundle diagnostics, remote support, and consumables to shift revenue toward higher-margin, recurring streams.
-
Hedge component risk: Enter strategic supply agreements for critical electronic modules and steel, and qualify alternate vendors to reduce single-source exposure.
-
Segment GTM by buyer economics: Align pricing and feature sets to the economics of distinct buyer groups—fully automatic platforms for high-throughput shops; semi-automatic, cost-efficient models for independents.
-
Use M&A tactically: Target acquisitions that fill capability gaps (software, connectivity, diagnostics) more often than scale alone; integration speed should be a gating criterion in 2026.
How to use this report in board-level conversations
Bring the report’s scenario models and ROI tool to your next strategic planning session. Use our sensitivity analyses to stress-test capital allocation decisions against commodity price swings and aftermarket adoption curves. For boards considering inorganic growth, the M&A scoring framework converts qualitative fit into quantitative trade-offs, making it easier to evaluate competing bids or divestiture options.
Conclusion — the strategic edge PW Consulting provides
For executives making pivotal 2026 decisions, the balance between speed and selectivity is decisive. PW Consulting’s report translates market scale and growth tempo into executable commercial and product strategies while exposing supply-chain and regulatory hazards that can erode margins if unaddressed. The report is not a replacement for internal analysis; it is a force-multiplier: validated market sizing, competitor insight, and operational playbooks that accelerate confident, defensible choices.
Next steps
Access the full report for detailed company profiles, the complete forecast model, customizable ROI tools, and the supplier risk register that we intentionally summarized here. For executive briefings, customized workshops, or to license our forecast dataset, please visit the official PW Consulting report page.
For detailed analysis of this topic, please visit the official page: Worldwide Wheel Balancer With Touchscreen Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Shape Memory Alloys for Civil Engineering Market Poised to Grow at an 8.5% CAGR
By pmarketresearch, 2026-08-12
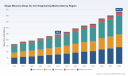
Worldwide Shape Memory Alloys for Civil Engineering Market — Strategic Intelligence to Guide 2026 Decisions
Executive snapshot
PW Consulting’s latest market study, Worldwide Shape Memory Alloys for Civil Engineering Market (base year 2025), equips infrastructure leaders with the strategic context they need to make disciplined investments in 2026. The global market has expanded from USD 165.2 Million in 2020 to USD 245.5 Million in 2025 (USD, Million) and is forecast to reach approximately USD 434.58 Million by 2032, reflecting a compounded annual growth rate of 8.5% across the 2026–2032 forecast window. These headline figures underscore a sustained, commercially meaningful adoption curve as owners, contractors and technology providers move from laboratory demonstrations to operational deployments across civil infrastructure applications.
RVs Lithium-Ion Energy Storage Batteries Market
Why this matters for 2026 decision‑makers
-
Accelerating retrofit and resilience agendas: Aging asset pools and more stringent resilience requirements make shape memory alloys (SMAs) an increasingly attractive lever for cost-effective strengthening, damping and adaptive elements in bridges, tunnels and building envelopes.
Worldwide Cotton Underwear Market -
Time‑to‑value becomes a competitive vector: SMA-enabled prestressing and thermal activation techniques can materially reduce on‑site labour, shorten outage windows and simplify sequencing for complex interventions — factors that change procurement calculus in 2026.
Worldwide Auxiliary Locks Market -
Material and regulatory dynamics are shaping opportunity windows: Nickel and titanium feedstock volatility is pressuring cost structures for NiTi solutions, while iron‑based SMAs (Fe‑SMA) are gaining traction because they can be produced using conventional metallurgical routes and are better positioned for large-scale civil deployments.
-
Standards and interoperability: Industry standards (including ASTM guidance applicable to SMA evaluation) are maturing, lowering technical risk and creating procurement benchmarks that buyers can use to specify performance and acceptance tests.
What PW Consulting’s report delivers — operational, decision‑ready content
This study is designed as a practitioner’s toolkit. It combines market intelligence with hands‑on instruments that procurement, engineering and strategy teams can deploy immediately:
-
Validated market sizing and a seven‑year forecast model (2026–2032) with scenario functionality so teams can stress‑test plans under alternative adoption and price paths.
-
Adoption curve maps and maturity matrices that show where different SMA technologies sit in the commercialization lifecycle — from early demonstrations to scale‑ready designs.
-
Use‑case ROI templates and decision trees that quantify expected downtime savings, labour reductions and life‑cycle benefits for retrofit, prestressing and damping applications.
-
Procurement playbooks and supplier due‑diligence checklists aligned to ASTM testing regimes and field acceptance protocols.
-
Supply chain heatmaps that identify single‑point material risks, cost drivers (including nickel/titanium exposure) and on‑shore/off‑shore production considerations.
-
Technical annexes translating laboratory measures (actuation temperatures, recovery stress, fatigue performance) into engineering acceptance criteria for design specifications.
-
Commercial model templates for win‑win contracting: EPC+SMA bundles, performance warranties and staged rollouts to de‑risk first‑of‑a‑kind projects.
-
Competitive landscaping with company profiles, capability scoring and partnership playbooks to support supplier selection and co‑development strategies.
Note: The report purposefully reserves granular revenue splits and detailed regional/application tables for subscribers; the “trailer” here highlights depth while directing practitioners to the full report for segment‑level intelligence and downloadable model files.
Competitive landscape — a strategic read on core suppliers
The SMA ecosystem for civil engineering is a mix of specialist innovators, materials manufacturers and component suppliers. Market concentration metrics indicate a horizontally fragmented market with consolidation potential: the top three suppliers account for a meaningful minority share while the top five widen that footprint further, signaling both room for new entrants and opportunity for strategic partnerships.
-
re‑fer AG (Brunnen, Switzerland) — Strengths: Proven iron‑based (Fe‑SMA) memory®‑steel solutions and a portfolio of real‑world civil applications (bridges, masonry repair, prestressing). Tactical implications: Owners seeking low‑temperature, scalable prestressing and retrofit solutions should prioritize pilot partnerships with Fe‑SMA specialists to validate lifecycle economics. Limitations: niche supplier scale compared with large metals manufacturers; co‑development and licensing deals may be required for mass deployment.
-
Ingpuls GmbH (Bochum, Germany) — Strengths: Customizable SMEs and integrated systems covering actuators, sensing and damping; full‑chain capability from specification to assembly. Tactical implications: Systems integrators and façade/MEP contractors should evaluate Ingpuls for turnkey actuator/detection prototypes that couple SMA hardware with building automation. Limitations: Transitioning from component to infrastructure scale requires strategic alliances with civil contractors and precasters.
-
SMA CORES Inc. (Champaign, USA) — Strengths: Focus on thermal prestressing and super‑elastic applications that can shorten construction time. Tactical implications: North American owners with compressed schedules should pilot SMA CORES’ approaches in targeted prestressing tasks to capture schedule and labour efficiencies.
-
SAES Getters S.p.A. (Lainate, Italy) — Strengths: Vertical integration across NiTi production, enabling tight quality control and component supply. Tactical implications: Buyers looking to manage material quality and traceability should engage vertically integrated producers for long‑lead contracts; caveat is NiTi exposure to raw material price swings.
-
Dynalloy Inc. (Irvine, USA) & Memry Corporation (Bethel, USA) — Strengths: Established suppliers of NiTi actuator wires, tubing and components used in actuation/damping niche applications. Tactical implications: These vendors are logical partners for integration into valve/ventilation/shading systems or for embedding sensing and actuation in civil structures where precision actuation is required.
Industry catalysts and near‑term developments
-
Research traction: Swiss researchers in collaboration with Empa demonstrated a heat‑activated Fe‑SMA method for strengthening ageing bridge decks, lowering the barrier to field adoption by validating activation protocols and performance in a civil context.
-
Knowledge consolidation: The Transportation Infrastructure Precast Innovation Center (TRANS‑IPIC) is convening the first International Symposium on Shape Memory Alloys in Infrastructure — a focal event expected to accelerate cross‑discipline knowledge transfer and standardization conversations.
-
Applied innovation: memory®‑steel has been used in digitally fabricated concrete elements (e.g., a staircase application in a research building), signaling that SMA incorporation into modern construction methods is not only possible but practical.
Key risks and regulatory levers
-
Raw material volatility: Nickel and titanium supply chains remain exposed to geopolitical and mining constraints — boards should bake material‑price stress tests into project cost models and consider hedging or long‑term supplier agreements.
-
Standards and acceptance: ASTM and related test methods are increasingly relevant; buyers should define acceptance criteria tied to standardized testing to mitigate performance disputes and to accelerate insurer and regulator confidence.
-
Scale and manufacturability: Fe‑SMA’s compatibility with conventional metallurgical processes offers a scale advantage for large civil elements; however, implementation logistics (activation equipment, thermal control) require operational readiness planning.
Strategic imperatives for 2026
-
Run focused pilot programmes on critical assets with measurable KPIs (downtime reduction, labour hours saved, life‑extension value) and a clear escalation path to portfolio rollout.
-
Design procurement around performance specifications linked to ASTM‑aligned tests rather than prescriptive material clauses — this opens competition while ensuring adequate quality control.
-
Diversify supplier exposure across NiTi and Fe‑SMA producers and build long‑term offtake clauses to manage feedstock pricing risk.
-
Invest in in‑house integration capability — small teams that can translate lab output into construction workflows (activation, monitoring, maintenance) will be a differentiator.
-
Negotiate collaboration agreements with specialty suppliers to secure IP access for scaling, and consider licensing or co‑development for site‑specific solutions.
-
Engage with standards bodies and symposiums to shape acceptance criteria and to accelerate insurer and regulator recognition.
Conclusion — how executives should use this study in 2026
For asset owners, contractors and materials investors, the 8.5% CAGR outlook and the trajectory from USD 245.5 Million (2025) toward mid‑hundreds of millions by 2032 signal the transition from niche experiments to selective mainstreaming. The strategic question for 2026 is not whether SMAs have technical merit, but how organisations will operationalise them: which pilot projects to fund, how to allocate procurement risk, who to partner with, and how to embed acceptance testing into contract packages.
PW Consulting’s report provides the forecast, the tools and the competitive analysis to answer those questions — and it reserves the granular segment and regional tables, along with downloadable financial models and procurement templates, for report subscribers. To access the full dataset, supplier scorecards and decision models that will directly support your 2026 investment and procurement decisions, please visit PW Consulting’s report landing page.
For detailed analysis of this topic, please visit the official page: Worldwide Shape Memory Alloys for Civil Engineering Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Niraparib Market Reaches USD 1,180.5 Million in 2025, Poised for a 12.43% CAGR to USD 2,680.5 Million by 2032
By pmarketresearch, 2026-08-12
Worldwide Niraparib Market: Strategic Imperatives for 2026 Decision‑Makers
As oncology portfolios and oncology-adjacent supply chains become defining pillars of biopharma growth strategies, niraparib has emerged from a specialist PARP inhibitor into a multi-indication strategic asset. PW Consulting’s latest Worldwide Niraparib Market report — with 2025 as the base year and a 2026–2032 forecast horizon — shows a market that reached roughly USD 1.18 billion in 2025 and is on track to approximately USD 2.68 billion by 2032, reflecting a compound annual growth rate (CAGR) of 12.43%. For executives preparing 2026 budgets, pipeline prioritization, licensing negotiations, or manufacturing investments, these headline dynamics translate into concrete choices that can materially affect shareholder value and patient access over the coming decade.
Medical Power Strip Market
Executive snapshot: why niraparib matters now
-
From maintenance therapy in ovarian cancer to newly approved prostate cancer combinations, niraparib has crossed from niche oncology drug to a diversified therapeutic platform with multiple commercial pathways.
Off-Grid Solar Lighting Market -
High market concentration around a small number of originator and license-holding firms creates both stability and strategic bottlenecks: a concentrated supplier and commercialization landscape amplifies the impact of regulatory decisions, label updates, and partnership shifts.
Worldwide Digital Manometer Market -
Regulatory and diagnostic advancements in late 2025–early 2026 materially changed the addressable population and payer dialogue — requiring rapid re-assessment of access models and commercial roll‑outs for 2026.
What this means for 2026 planning
-
Prioritize regulatory-readiness and label optimization. Recent label updates and the extension of indications into prostate cancer broaden the clinical use case, but also require updated HCP engagement, new value dossiers, and targeted payer evidence generation during 2026.
-
Refresh companion diagnostic strategies. The approval of an HRD companion diagnostic linked to niraparib use heightens the importance of diagnostic access, sample logistics, and co‑marketing agreements — all levers that influence uptake curves in the first 18 months post-approval.
-
Stress-test supply chains. A market trajectory that doubles within the forecast window increases demand volatility for both API and finished-dose forms. Organizations should model multi‑scenario capacity needs and validate secondary suppliers to mitigate single‑source exposure.
-
Revisit partnership and exclusivity timelines. Patent protection and exclusive licensing footprints remain central strategic constraints; organizations should align M&A, out‑licensing, and geographic expansion timelines to these IP and collaborator windows.
Report deliverables — practical, decision‑ready content
Our report is built as a playbook for commercial, regulatory, and manufacturing leadership. Key operational modules include:
-
Market-sizing and scenario modeling: Transparent methodology, sensitivity analyses, and regional uptake scenarios that map to different reimbursement and diagnostic penetration trajectories.
-
Go‑to‑market playbooks: Segmented launch strategies by stakeholder (oncologists, urologists, payers), channel tactics, and recommended evidence generation plans for label expansions.
-
Competitive intelligence and partner maps: Deep profiles of originators, licensees, and active API/FDF suppliers, with strategic implications for pricing, tendering, and co‑promotion opportunities.
-
Regulatory and HTA tracker: Rolling timeline of approvals, label updates, diagnostic authorizations, and payer coverage decisions that influence near‑term access.
-
Manufacturing and sourcing playbook: API capacity assessments, quality/regulatory audit priorities, and contingency sourcing strategies for rapid scale‑up.
-
M&A and licensing scorecards: Value drivers, downside scenarios, and negotiation playbooks tailored to acquirers, licensors, and regional partners.
Competitive landscape: players, positions, and strategic levers
The competitive field for niraparib is shaped by a mix of originator companies, regional licensees, and specialist API suppliers. The market is highly concentrated among a few leading commercial principals — a dynamic we quantify in the report and that materially raises the strategic value of control over commercialization rights and label breadth.
-
Originator and global commercial steward: The originator remains the primary commercial force behind ZEJULA (niraparib), managing global brand stewardship, lifecycle management, and evidence generation in core indications. Their stewardship dictates global messaging, safety updates, and the timing of major labelling changes.
-
Prostate‑focused collaborator: A major multinational holds exclusive rights (outside certain territories) to advance niraparib combinations in prostate cancer and has successfully brought a dual‑action combination to approval in late 2025. This creates a parallel commercial track that complements ovarian cancer maintenance use and expands prescriber audiences.
-
Regional licensees and partners: Strategic commercialization partners in Greater China and Japan retain critical in-market capabilities and distribution networks — decisions on promotional investments and diagnostic partnerships in these territories will determine near-term market penetration.
-
API and manufacturing base: A set of established API manufacturers and regional suppliers underpin global production. Their capabilities, GMP certifications, and willingness to scale are determining factors in the cost curve and supply resilience during peak demand periods.
Recent developments that alter the playbook
-
Late‑stage regulatory approvals and Priority Review actions in 2025 materially shift the addressable population and accelerate commercialization plans for combination regimens in prostate cancer.
-
Companion diagnostic authorization in early 2026 refocuses market access conversations around biomarker-driven reimbursement and necessitates integrated diagnostic‑drug launch plans.
-
Originator label updates and updated prescribing information (2025) change clinical positioning and risk mitigation communications, which should be reflected in medical affairs roadmaps and safety monitoring strategies.
Risk map for 2026 decisions
-
IP timeline sensitivity: Core composition and formulation patents extend into the late 2030s, shaping generic entry timing and informing licensing valuations. Executives must model multiple scenarios for post‑patent competitive intensity.
-
Diagnostic adoption uncertainty: Uptake of companion diagnostics is uneven by market; slow diagnostic access undermines the projected addressable population and requires bespoke access strategies per market.
-
Supply concentration: With a limited set of qualified API and FDF suppliers, capacity constraints or GMP disruptions could create outsized commercial effects during rapid uptake phases.
-
Payer negotiation pressure: Broader indications and combination regimens increase absolute spend per patient, inviting tougher HTA scrutiny and price negotiation in several major markets.
Actionable recommendations for 2026
-
Align evidence generation with payer windows. Prioritize health economic studies and real‑world evidence protocols that address the most likely HTA objections for combination therapies and biomarker‑selected indications.
-
Fast‑track diagnostic partnerships. Secure preferred diagnostic pathways early (lab network agreements, co‑payment solutions, or companion kit distribution) to reduce friction at launch.
-
Strengthen supplier redundancy. Validate alternate API sources and build staged inventory buffers tied to launch milestones rather than to fixed calendar dates.
-
Negotiate geographic rights with optionality. Structure deals with step‑in rights and performance milestones to protect upside across label expansions and geographic diffusion.
Why PW Consulting’s report matters to you
For 2026, niraparib is both an operational challenge and a strategic growth lever. Our report delivers not only a rigorous market sizing — rooted in transparent assumptions and sensitivity analyses — but also actionable modules that translate forecasts into procurement decisions, clinical trial planning, and commercial timelines. We surface the implications of recent regulatory movements, diagnostic approvals, and label changes, and we map the supplier and partner landscape that will determine who wins the next phase of adoption.
Next steps — where to find the data you need
This article intentionally highlights the strategic breadth of the opportunity without disclosing granular regional or indication splits; the full report contains the detailed segmentation tables, regional uptake curves, pricing scenarios, and supplier scorecards that underpin the headline market trajectory. Senior leaders requiring transaction support, bespoke scenario runs, or onboarding briefings can request tailored appendices and interactive models directly from PW Consulting.
To convert the 2026 market opportunity into commercial advantage, organizations should move quickly to synchronize evidence plans, diagnostic access, and supply assurance. PW Consulting’s Worldwide Niraparib Market report is designed to be the roadmap for that work.
For detailed analysis of this topic, please visit the official page: Worldwide Niraparib Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Fully Automatic Tofu Machine Market to Climb from USD 485.6 Million in 2025 to USD 752.13 Million by 2032, Powered by a 6.45% CAGR
By pmarketresearch, 2026-08-12
Worldwide Fully Automatic Tofu Machine Market — Strategic Outlook for 2026 Decision-Makers
Executive snapshot
PW Consulting’s latest market study on the Worldwide Fully Automatic Tofu Machine Market delivers a focused, decision-ready perspective for executives shaping 2026 strategy. The market has matured into a multi-hundred‑million-dollar global sector—expanding from roughly USD 355.2 Million in 2020 to an estimated USD 485.6 Million in 2025—and our base-case forecast projects sustained momentum through the 2026–2032 period at a compound annual growth rate (CAGR) of 6.45%. By 2032 the market is modeled to approach USD 752.13 Million under the baseline scenario.
Worldwide Tire Inflators Market
Why this matters for 2026 strategy
- Investment timing: The near-term growth trajectory signals attractive windows for capacity expansion, retrofits, and greenfield projects, but timing matters—cost pressures and technology cycles are compressing payback horizons.
- Product and channel plays: Automation is shifting competitive advantage from basic equipment supply toward integrated, turnkey solutions that shorten time-to-market for manufacturers and retailers alike.
- Risk management: Raw-material volatility and energy costs require operating models that hedge input exposure via procurement strategy and technical investments in energy and water efficiency.
Data-driven market trajectory (what the numbers tell you)
Historic patterns show steady expansion from 2020 through 2025, with CAGR pickup in the most recent years as automation adoption accelerated across food processors, commercial kitchens and retail manufacturing initiatives. Our forecast through 2032 incorporates multiple drivers—demand for plant‑based products, labor substitution via automation, and regulatory harmonization on food safety—that produce a mid-single-digit growth profile (6.45% CAGR) out to the end of the forecast horizon.
Worldwide Embedded Vision Systems Market
For corporate decision‑makers, the implication is clear: the sector’s growth is large enough to justify strategic commitments (R&D, production capacity, and channel development) while remaining tractable—market concentration is moderate, with the three largest vendors controlling roughly one‑third of market value and the top five representing under half, leaving room for regional specialists and differentiated technology providers to win.
Nickel-Metal Hydride Button Cell Market
Key macro and operational dynamics to watch in 2026
- Input-cost inflation: Soybean and commodity inputs have shown meaningful year‑over‑year price movement; procurement and process optimization will determine margin resilience.
- Labor scarcity and automation: Fully automatic systems materially reduce manual touchpoints across soaking, grinding, coagulation and pressing—translating into predictable labor savings and quality consistency that many food processors now treat as table stakes.
- Regulatory alignment and certifications: ISO and CE compliance are increasingly embedded in buyers’ RFPs; vendors who can demonstrate certified hygienic design will access premium channels such as export food manufacturers and large retailers.
- Sustainability and energy efficiency: Advances in high‑efficiency heating, heat recovery and water recycling are shifting total cost of ownership (TCO) equations—making capital investment in energy‑saving modules a high‑priority lever for cost-conscious operators.
Strategic implications by functional agenda
- Senior executives / corporate strategy: Prioritize a dual path of selective capacity expansion in regions where demand acceleration and regulatory access align, plus a targeted M&A scouting effort to acquire niche automation or energy‑savings technologies that shorten innovation cycles.
- Operations and engineering: Re-evaluate retrofit opportunities; modular automation upgrades often deliver faster ROI than full-line replacements in mid‑sized facilities.
- Supply chain & procurement: Shift toward longer-term soybean contracts, blended sourcing strategies, and collaboration with machine vendors for spare-part logistics to reduce downtime risk.
- Commercial and channel leaders: Differentiate through service models—embedded maintenance contracts, remote diagnostics, and ingredient-to-package turnkey solutions increase customer stickiness and open annuity revenue streams.
Competitive landscape — what the market structure means for 2026 moves
The marketplace combines legacy engineering houses, regional manufacturers, and agile mid-size OEMs. Our competitive scan highlights several archetypes that buyers and investors should recognize:
- Heritage engineering champions: Companies with long histories in soy and tofu plant engineering deliver high‑throughput, industry‑grade lines and global turnkey experience—well suited to large processors seeking scale and export capability.
- Certified turnkey specialists: Vendors offering ISO/CE certified European‑style lines and mid‑to‑high capacity dry soybean processing solutions are positioned to win institutional food‑manufacturing contracts and multi-site rollouts.
- Cost‑competitive regional suppliers: Numerous suppliers focus on stainless‑steel, commercial‑grade equipment for local and regional markets, delivering attractive unit economics for SMEs and specialty producers.
- Emerging innovators: A cadre of firms is embedding energy efficiency, modular control systems and digital diagnostics—capabilities that increasingly decide tenders that emphasize TCO over upfront price.
Representative profiles from our company analysis:
- Takai Tofu & Soymilk Equipment Co. (Japan): A century‑scale specialist delivering high‑speed fully automatic lines with large daily pack capacities and a global delivery footprint—an archetypal partner for large industrial processors.
- Yung Soon Lih Food Machine Co., Ltd. (Taiwan): Offers certified turnkey lines and a spectrum of throughputs for dry soybean processing and specialty tofu types; active in trade shows and international marketing to build global OEM relationships.
- China‑based OEMs (representative): Several manufacturers provide integrated machines that combine soaking, grinding, filtering, boiling and pressing into compact footprints—well suited to commercial kitchens, co‑packers and smaller factories.
- Indian suppliers (representative): Firms supplying reliable stainless‑steel machines for regional markets at competitive price‑performance levels are addressing growing domestic demand for processed plant protein products.
Recent industry developments shaping 2026 opportunity
- Major equipment suppliers continue to showcase automation advancements at international trade shows—an indicator that suppliers are investing in product visibility and global distribution.
- Raw‑material price movements and national season‑average forecasts have increased procurement focus among processors; advanced buyers are tying equipment purchase timing to hedged input strategies.
- Regulatory and certification alignment (ISO/CE) remains a gating factor for vendors seeking to participate in cross‑border procurement programs; certification now appears routinely in vendor evaluation matrices.
What our full report provides (practical, actionable content)
The PW Consulting study is structured to equip executives with both strategic context and operational tools. Subscribers will find:
- Market sizing and scenario forecasts (2020–2032) with sensitivity testing across commodity, energy and adoption curves.
- Go‑to‑market playbooks for OEMs, co‑packers and retailers—covering pricing, service models, and channel partnerships.
- Detailed vendor benchmarking and supplier selection matrices—including quality certification status, throughput bands, modularity, and TCO estimates.
- CapEx and OpEx modeling templates that integrate energy, water and labor inputs to support investment appraisal and payback analysis.
- Regulatory and sustainability checklists to streamline international market entry and buyer due‑diligence.
To preserve the report’s commercial value while enabling executive triage, this release intentionally highlights high‑confidence findings and strategic implications; detailed regional splits, application‑level shares and full company financials are distilled in the report itself.
Recommended next steps for 2026
- Run a one‑week internal TCO exercise using our modeling templates to re‑rank near‑term capital projects.
- Prioritize supplier audits that verify hygienic design and energy efficiency claims; certifications should be contractually required for export‑oriented lines.
- Explore pilot partnerships with turnkey vendors that include performance guarantees and remote monitoring—lowering the cost of technology adoption while proving concepts at scale.
- Align procurement timing with commodity hedges to protect margin during machine commissioning and ramp‑up phases.
How to obtain the full market intelligence
This briefing outlines the high‑value, strategic takeaways from PW Consulting’s Worldwide Fully Automatic Tofu Machine Market report and emphasizes the near‑term decisions that will shape competitive positioning in 2026. The full report contains the granular segmentation tables, regional and application breakdowns, extended vendor profiles, and downloadable financial models required to implement the actions recommended here. Access to the complete dataset and appendices is available via PW Consulting’s report distribution channels.
For teams committed to converting 2026 opportunity into measurable advantage, the full report is the operational playbook—containing the confidential tables and scenario outputs that underpin these recommendations. Contact PW Consulting to request the report package and a tailored briefing for your executive team.
For detailed analysis of this topic, please visit the official page: Worldwide Fully Automatic Tofu Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Cell Controller Market to Grow at 8.45% CAGR, Reach USD 1.315 Billion by 2032
By pmarketresearch, 2026-08-12
Worldwide Cell Controller Market 2026: Strategic Imperatives from PW Consulting’s New Industry Brief
As organizations calibrate strategic plans for 2026, decisions around battery architecture, supplier selection, and safety compliance will increasingly shape competitive advantage. PW Consulting’s latest Worldwide Cell Controller Market research — built on a 2025 base year and a 2026–2032 forecast horizon — translates market dynamics into actionable guidance for OEMs, Tier‑1 suppliers, semiconductor vendors, energy storage developers, and private equity sponsors evaluating the electrified mobility and energy sectors.
Worldwide Solder Mask Market
Why cell controllers matter now — and why 2026 is a hinge year
Cell controllers sit at the interface of electrochemistry and systems engineering. They govern voltage and temperature sensing, cell balancing, fault isolation, and the safety instrumentation necessary to meet automotive and industrial safety standards. Our analysis traces a rapid maturation: the global market expanded from approximately USD 498 million in 2020 to roughly USD 746 million in 2025, a near‑50% increase over five years. Looking forward, the market is set to accelerate under a structural mix of EV adoption, stationary storage deployments, higher cell counts per pack, and rising functional‑safety expectations — a compound annual growth rate of 8.45% across the 2026–2032 forecast window, with the market crossing the USD 1.3 billion threshold by 2032.
Talc Ceramic Sleeve Market
For executives planning 2026 roadmaps, this is not a distant technical nuance: choices made this year about chip architectures, communication stacks, and supplier partnerships will determine cost curves, certification timelines, and time‑to‑market for next‑generation battery systems.
Data Center Virtualization Service Market
What the report delivers — pragmatic intelligence for decision makers
- Forward‑looking market sizing and scenario‑based forecasts calibrated to 2025 baseline metrics and stress‑tested across alternate EV and ESS adoption paths.
- A regulatory and standards playbook that aligns product roadmaps to ISO 26262, ISO 12405 series guidance, and functional‑safety testing regimes relevant to automotive and industrial deployments.
- Technology maps that decode cell controller architectures (isolated daisy‑chain communications, transformer physical layers, per‑cell ADC strategies, and telemetry/security overlays) and translate them into modular design patterns for hardware and software teams.
- Commercial frameworks: supplier scorecards, TCO models that combine silicon, BOM, and software/service monetization, and sourcing strategies for dual‑sourcing and qualification acceleration.
- Competitive intelligence dossiers and M&A playbooks: comparative vendor heat maps, capability cluster analysis, and diligence checklists for bolt‑on acquisitions or strategic partnerships.
- Implementation checklists and test bench templates (including virtualization and hardware‑in‑the‑loop scenarios) that cut validation cycles and reduce field recall risk.
We intentionally keep headline data public while reserving granular breakouts, vendor revenue shares, and region/application splits for the full report — because those details function as executional playbooks for clients.
Market structure and competitive dynamics: concentrated, but open to disruption
The cell controller market today exhibits moderate concentration. The top three vendors account for just over 40% of global share, and the top five approach roughly 59% — a structure that creates both stability and opportunity. Incumbent semiconductor giants command design wins with robust functional‑safety features and broad ecosystem support, yet mid‑tier specialists and software‑centric firms are carving differentiated positions around virtualization, service layers, and domain‑specific integrations.
Strategically, this concentration implies two viable client pathways in 2026:
- For OEMs and Tier‑1s: standardize around established silicon partners to shorten certification cycles, while maintaining an innovation sandbox with specialist vendors to mitigate supplier risk and capture value from differentiated features.
- For investors and new entrants: target software and test‑infrastructure assets that can scale across chipset vendors — these assets deliver high margin expansion and act as gateway technologies into broader BMS revenue pools.
Vendor spotlights — what to watch in 2026
Our competitive analysis spotlights several firms that exemplify distinct strategic postures in the cell controller value chain:
- NXP Semiconductors (Eindhoven) : NXP continues to expand its portfolio with high‑channel count ICs and functional‑safety credentials tailored for HVBMS and ESS. A notable milestone in mid‑2025 was a new family of 18‑channel cell controller ICs incorporating per‑channel ADCs, pin‑compatibility across variants, and hardware safety signaling designed to meet ASIL‑C (automotive) and SIL‑2 (industrial) requirements. For adopters, NXP’s value lies in integrated safety features, proven automotive qualification pathways, and broad ecosystem support; for partners, its platform provides a stable foundation but can carry premium pricing and qualification lock‑in risks.
- Texas Instruments (Dallas) : TI plays to its analog and system‑level strengths with cell monitor and balance ICs that facilitate rapid pack-level integration and manufacturing scale. Expect TI to push software toolchains and reference designs that reduce OEM integration effort — attractive for high‑volume industrial customers eyeing reduced time‑to‑certification.
- Analog Devices (Wilmington) : Analog Devices emphasizes precision measurement and isolation technologies, positioning its devices for high‑voltage, high‑accuracy applications (such as aerospace and premium EV segments). Its strategic advantage will be in markets where measurement fidelity links directly to system efficiency and warranty risk reduction.
- dSPACE (Paderborn) : As testing and virtualization become decisive, dSPACE’s cell controller virtualization (CCV) offerings enable manufacturers to validate BMS strategies across multi‑vendor controllers in software‑centric workflows. This lowers development cost and accelerates validation against functional‑safety requirements — an increasingly vital capability as cell counts and software complexity rise.
Together these vendors illustrate the market’s dual thrust: silicon‑led reliability and software/virtualization‑led speed to market. The interplay between these vectors will define winners in 2026 and beyond.
Regulatory and technical guardrails shaping strategy
Regulatory expectations are converging on demonstrable functional safety and rigorous diagnostics. ISO 26262 remains the de facto safety framework for automotive applications, and the ISO 12405 family explicitly references cell electronics and controller requirements for electrically propelled vehicles. Practically, this means suppliers and integrators must embed diagnostic coverage, redundant sensing, and fail‑safe communication layers early in product development.
From a systems architecture perspective, isolated daisy‑chain communication and transformer‑based physical layers are becoming standard approaches to manage reliability across long strings of cells. These choices have implications for connector design, EMC planning, and serviceability strategies. Firms that align their roadmaps to these technical guardrails — and demonstrate shortened verification cycles — will capture disproportionate share of design wins in 2026.
Actionable playbook for 2026 decision‑makers
- Prioritize platform‑level compatibility: Select cell controllers and companion software that are modular, support isolated daisy‑chain topologies, and provide clear migration paths across safety levels. This reduces rework as pack architectures evolve.
- Dual‑track certification: Run parallel paths: a low‑risk track that leverages proven silicon for near‑term models and an innovation track that pilots newer architectures in limited production runs.
- Invest in virtualization: Adopt CCV and HIL frameworks to compress validation timelines. Our fieldwork shows virtualization can cut late‑stage integration issues by over 30% in complex pack programs.
- Balance CapEx and OpEx via software services: Given the growth trajectory, software and services tied to cell controllers (analytics, OTA updates, health prognostics) are high‑leverage monetization channels that also improve pack lifecycle economics.
- Make procurement decisions with concentration in mind: The market’s top vendors control significant share; however, targeted partnerships with specialists can yield differentiated features without wholesale vendor lock‑in.
Closing — the strategic value of granular intelligence
2026 will be a decisive year for companies positioning themselves in the electrification value chain. The cell controller market is no longer a purely technical consideration; it is a strategic lever that influences safety certification timelines, product cost curves, and after‑sales economics. PW Consulting’s Worldwide Cell Controller Market report combines market sizing anchored to a 2025 baseline, an 8.45% CAGR forecast across 2026–2032, and pragmatic playbooks to turn those forecasts into executable strategies.
For executives and investment teams preparing 2026 plans, the report provides the granular intelligence needed to align product roadmaps, prioritize vendor engagements, and identify acquisition targets — while the reserved detailed segment tables and vendor revenue breakdowns serve as the tactical playbook available exclusively in the full report.
To access the comprehensive datasets, scenario models, vendor dossiers, and implementation templates referenced here, please visit the PW Consulting report page and request the full Worldwide Cell Controller Market brief.
For detailed analysis of this topic, please visit the official page: Worldwide Cell Controller Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Packaging Outserts & Inserts Market to Grow from USD 4,624.9 Million in 2025 to USD 6,954.1 Million by 2032 at a 6.0% CAGR
By pmarketresearch, 2026-08-12
Packaging Outsert and Inserts Market — Strategic Preview for 2026: Key Imperatives from PW Consulting’s New Study
PW Consulting’s latest market intelligence brief — the Packaging Outsert and Inserts Market report (base year 2025) — synthesizes five-year historical performance and a forward-looking forecast to 2032, delivering a concise strategic playbook for business leaders navigating the supplier, innovation, regulatory, and cost pressures that will define 2026. The market demonstrated sustained expansion through 2020–2025, reached an estimated USD 4,624.9 Million in 2025, and is projected to continue its upward trajectory in 2026 and beyond, underpinned by a modeled mid-single-digit compound annual growth rate (CAGR) of 6.0% over the forecast horizon.
Smart Community Solutions Market
Why this report matters to decision-makers in 2026
- Actionable market context: The study converts aggregate growth and demand signals into priority actions—capacity planning, supplier selection, and product roadmaps—so procurement, packaging engineering, and regulatory affairs teams can align tactical moves to a predictable market cadence.
- Regulatory inflection points: With major EPR (Extended Producer Responsibility) regimes expanding in the U.S. and the EU’s Packaging and Packaging Waste Regulation coming into effect, packaging owners must reconcile compliance timelines with sourcing and design changes. Our report ties regulatory milestones to incremental cost and supply interventions.
- Cost and input-risk visibility: Paperboard and pulp cost volatility has a measurable impact on unit economics for outserts and inserts. The brief models sensitivity scenarios so teams can stress-test supplier contracts, hedging options, and design-for-cost trade-offs.
- Competitive benchmarking: We distill vendor capabilities into decision-oriented diagnostics that support make-or-buy, nearshoring, and supplier consolidation choices in markets where the top-tier suppliers account for a relatively small share of total industry sales.
Report scope and practical deliverables
This study is designed as an operational resource, not just a high-level overview. Key practical inclusions are:
Frozen Fruit Bar Market
- A validated topline market model (historical 2020–2025 and forecast 2026–2032) that quantifies demand growth under alternate macro-economic and regulatory scenarios, including sensitivity to material cost swings and regulatory compliance costs.
- Scenario-based cost models that let users populate their own input assumptions (paperboard, pulp, digital printing premiums, automation CAPEX and labor shifts) to calculate unit cost and margin impact across different production strategies.
- Supply-chain heatmaps and risk matrices showing where capacity constraints, raw-material exposure, and regulatory-driven redesign risk are most likely to appear—presented as decision triggers for sourcing and capital allocation.
- A vendor capability framework and scorecard templates for evaluating suppliers on regulatory compliance (cGMP/ISO), print quality, fold and conversion technology, digital printing readiness, and scale economics.
- Implementation-ready playbooks: procurement negotiation checklists, sample KPI dashboards for packaging operations, and a phased sustainability roadmap to meet emerging EPR and recycled-content obligations.
Market structure and competitive dynamics
The outsert and inserts sector remains fragmented: our concentration analysis shows that the three largest suppliers capture under 20% of market revenues, while the top five remain below one-quarter of industry sales—an important strategic signal. Low concentration implies of-the-moment opportunities for consolidation, targeted vertical integration by strategic buyers, and differentiated service offerings by tier-two and regional specialists.
Food Grade Softening Resin Market
Leading suppliers illustrate divergent strategic plays:
- Winpak (Norwood, NJ; https://www.winpak.com) — leverages precision conversion and pharmaceutical-grade compliance to deliver MedGuides, IFUs and large-format-to-compact conversions suited for automated application on bottles and cartons. Their recent product introductions point to continued productization of high-precision inserts.
- CCL Healthcare (Etobicoke, ON; https://cclhealthcare.com) — positions itself on customization scale and regulatory multilingual capabilities, producing extensive panel counts and long-form booklets under cGMP and ISO environments to serve multinational pharma needs.
- Nosco (USA; https://www.nosco.com) — emphasizes advanced folding and stitched booklets, targeting regulatory consistency and repeatability across high-panel-count applications for pharma and CPG clients.
- Colbert Packaging (Kenosha, WI; https://colbertpkg.com) — combines custom carton manufacturing with high-capacity micro-folding systems; a recent capacity expansion (new blanking die cutter, March 2026) underlines expectations for renewed demand in paperboard-based solutions.
- Graphic Packaging International (global; https://www.graphicpkg.com) — integrates leaflet and carton design with targeted paper grades for mandatory safety literature, competing on system-level solutions that reduce secondary packaging complexity.
- Faller Packaging (Waldkirch, Germany; https://www.faller-packaging.com) — focusing on pharma system supply in Europe and digital printing adoption (notably digital leaflet printing expansions in 2025) to shorten lead-times and support variable content needs.
- RLG Healthcare, Tursso, Flottman and others — occupy specialized niches (high-panel patient leaflets, IFUs for devices, miniature precision inserts) and form a resilient middle market that supplies technically demanding pharma applications.
These competitive archetypes—scale/system suppliers, precision/regulatory specialists, and digitally-enabled short-run providers—map directly to client strategies in our report: whether the right move is to partner, co-develop, insource, or acquire.
Key dynamics shaping 2026 planning
- Raw-material volatility: Recent data points show month-to-month movements in packaging-related producer price indices and persistent sensitivity in wood-pulp markets. For example, U.S. producer price indices for folding paperboard boxes and related packaging components have displayed near-term moderation, while global wood-pulp import/export spreads remain material for producers that do not hedge or pass costs to customers. The report contains templates to translate index moves into unit-cost deltas for contract negotiations.
- Regulatory acceleration: A wave of Extended Producer Responsibility laws across multiple U.S. states and the EU’s PPWR (effective August 2026) shift lifecycle costs onto producers and demand upstream redesigns—especially for mixed-material and non-recyclable laminates. Our regulatory-impact module brings these obligations into 3-year CAPEX and sourcing plans.
- Digital and automation inflection: Investments in variable-content digital printing, inline folding/gluing, and automation for in-line application are changing the economics for short-run, multi-language, and serialized literature—enabling new just-in-time strategies for patient materials and promotional leaflets.
- Fragmented supply base, targeted consolidation: Low top-tier share creates acquisition and partnership windows for organizations seeking to secure capability gaps (micro-folding, high-panel count production, regulatory printing) and to build geographic resiliency.
Practical recommendations for 2026
For executive teams seeking concrete next steps, the study prioritizes a short list of actions with measurable outcomes:
- 0–12 months — Execute supplier stress tests using our cost-sensitivity templates; secure short-term price collars or indexed contracts for paperboard/pulp exposure; launch a supplier capability audit focused on digital printing and serialization readiness; evaluate immediate OEM partnerships to manage EPR administrative compliance.
- 12–36 months — Invest in selective automation and digital print capacity (own or partner) to reduce lead-times and enable personalization; pursue targeted M&A or JV opportunities to acquire specialized folding or high-panel-count capabilities; implement circular-design pilots aligned to foreseeable recycled-content mandates and EPR reporting requirements.
- Commercial and regulatory — Rework SLAs and quality gates to include cGMP/ISO evidence, digital file management workflows, and change-control processes that reduce recall risk and rework on regulated pharmaceutical literature.
What we deliberately leave for the full report
This release is intended as a strategic preview. To preserve the value of our proprietary segmentation and supplier-scorecard outputs — which include granular regional and application-level demand allocations, detailed supplier cost benchmarking, and payback schedules — readers are directed to the full report. Those datasets power the tactical models and vendor-selection tools that teams will use to operationalize the recommendations above.
Next steps and how to access the study
PW Consulting’s Packaging Outsert and Inserts Market report combines empirical market modeling with practical implementation tools for procurement, packaging engineering, regulatory and sustainability teams preparing for 2026. For access to the full dataset, vendor scorecards, and scenario worksheets that underpin the recommendations summarized here, please visit our report page or contact our research team for a tailored briefing.
About PW Consulting: We advise Fortune 1000 and mid-market clients on packaging, supply-chain resilience, and regulatory strategy. Our market studies are built to translate industry dynamics into executable plans and measurable KPIs.
For detailed analysis of this topic, please visit the official page: Packaging Outsert and Inserts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide SPECT Camera Market to Expand at a 6.02% CAGR Through 2032
By pmarketresearch, 2026-08-12
Worldwide SPECT Camera Market: Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide SPECT Camera Market delivers a focused, action-oriented intelligence package designed to influence capital allocation, product strategy, and go-to-market planning in 2026. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, the report synthesizes primary interviews, vendor benchmarking, regulatory mapping, reimbursement analysis, and scenario-based financial models to surface near-term inflection points and durable competitive advantages.
Worldwide Virtual Office Market
Why this briefing matters for 2026
-
Macro trajectory: The global SPECT camera market—measured in USD millions—continues to expand from a 2025 baseline, with modelled output showing a near-term uplift in 2026 and a compounded annual growth rate of approximately 6.02% across the forecast period. This trajectory implies both incremental volume opportunities and rising pressure to differentiate along software, digital detector, and service dimensions.
Traffic Aggregators Market -
Consolidation signal: Market concentration is meaningful—our CR3 and CR5 metrics indicate a high degree of share control among leading incumbents, reinforcing that scale, installed-base service economics, and regulatory footprint are decisive competitive assets.
Worldwide Site Management Organization Market -
Decision window: 2026 represents a strategic window for procurement and product investment decisions: buyers will balance legacy fleet upgrades with adoption of hybrid and digital solutions; vendors must prioritize clinical evidence, reimbursement alignment, and workflow-centric AI to capture premium segments.
Core findings (high-level, non-granular)
-
Growth drivers: Aging populations in developed markets, expanding oncology and cardiology imaging volumes, and continued clinical validation of SPECT/CT hybrid workflows are the primary demand engines. Parallel advances in detector technology (including cadmium zinc telluride / CZT and digital solid-state sensors) and AI-enabled reconstruction/quantification are increasing effective throughput and diagnostic yield.
-
Technology bifurcation: The market is evolving along two complementary axes—hardware modernization (hybrid SPECT/CT, digital detectors, advanced collimation) and software-enabled workflow/value capture (AI reconstruction, automated quantification, and cloud-enabled enterprise services).
-
Commercial economics: Service revenues, consumables, and upgrade packages are becoming a larger share of lifetime value per installed system. For capital-constrained customers, bundled financing and outcome-linked service agreements will be decisive.
-
Regulatory and reimbursement dynamics: SPECT cameras are regulated as Class II devices under established device codes and require 510(k) notifications in the U.S.; procedure coding and DRG structures materially influence adoption economics across payers. Compliance with international quality and QC standards remains a gating factor for procurement.
What the report contains — practical deliverables for executives
-
Market sizing and scenario modelling: Top-down and bottom-up models from 2020 through 2032, including baseline, conservative, and upside scenarios that stress-test device replacement cycles, modality substitution, and reimbursement shifts.
-
Competitive playbooks: Vendor scorecards, product roadmaps, patent and clinical-trial intelligence, and go-to-market matrices that identify where each supplier can win or is vulnerable.
-
Clinical and technology assessment: Comparative analysis of detector technologies, AI-enabled reconstruction, and hybrid SPECT/CT architectures with guidance on clinical use-cases, throughput trade-offs, and dose-optimization strategies.
-
Reimbursement and regulatory navigator: A practical section mapping CPT/DRG implications, 510(k) pathways, and relevant standards (including minimum performance and QC standards), with recommended compliance checklists for procurement and clinical adoption.
-
Commercial models and procurement templates: Total-cost-of-ownership calculators, service-contract templates, and outcome-based contracting frameworks designed for hospital systems and imaging network consolidators.
-
M&A and partnership intelligence: Target screening, valuation multiples, and integration playbooks for investors and strategic buyers seeking scale, technology access, or geographic expansion.
Competitive landscape — strategic implications
-
Incumbent OEM strengths: Leading multinational vendors bring deep installed bases, broad regulatory clearances, and global service networks—advantages that enable premium pricing for hybrid solutions and rapid platform rollouts. They also invest heavily in AI-enabled workflow and quantification to lock in clinical workflows.
-
Disruptive specialists: Technology-focused entrants leveraging CZT and digital detectors are redefining performance benchmarks—faster scans, higher energy resolution, and targeted cardiac/oncology applications—creating opportunity to displace legacy platforms in specialized centers of excellence.
-
Regional challengers and vertically integrated solutions: Newer players combining system design with local manufacturing or tailored financing models can accelerate adoption in price-sensitive markets, particularly where service and spare-part economics are optimized for local scale.
-
Recent regulatory milestones: A sequence of clearances for advanced SPECT/CT and CZT-based systems in recent years has lowered clinical adoption barriers for higher-performance devices, while reinforcing the need for robust clinical evidence and post-market performance monitoring.
Key vendors examined
-
GE HealthCare — positioning: Broad SPECT/CT portfolio with targeted cardiac and oncology quantification capabilities; strength in global service and clinical partnerships.
-
Siemens Healthineers — positioning: Integrated AI workflows and recent regulatory clearances for intelligent SPECT/CT platforms; emphasis on productivity and standardized exam protocols.
-
Philips Healthcare — positioning: Low-dose optimized systems with strong clinical protocols for cardiac and oncology; focus on dose management and image quality trade-offs.
-
Spectrum Dynamics Medical — positioning: CZT-centric systems offering substantially higher count sensitivity and spatial resolution, enabling faster exams and new clinical applications.
-
United Imaging Healthcare — positioning: Rapidly scaling digital-detector offerings with integrated whole-body SPECT/CT solutions targeted at high-throughput oncology and cardiology centers.
-
Mediso — positioning: Niche expertise across preclinical and clinical SPECT/CT products with focused application support for translational imaging workflows.
Regulatory, reimbursement and standards landscape
-
Regulation: SPECT cameras fall under established device classification frameworks requiring premarket notifications; recent device clearances for AI-enabled systems signal regulatory receptivity when clinical benefits are demonstrated.
-
Reimbursement: Existing procedure codes and DRG classifications materially influence capital recovery timelines. Providers and vendors must synchronize clinical validation with payer engagement to secure favorable reimbursement trajectories.
-
Standards & quality: Adherence to international QC and performance standards is a minimum requirement for procurement in most systems; robust QC protocols also reduce operational risk and total cost of ownership.
Strategic recommendations for stakeholders (2026-ready)
-
For OEMs: Prioritize hybrid SPECT/CT and digital-detector upgrades where clinical outcomes and throughput uplift can be demonstrated. Bundle AI-driven workflow, remote service, and outcome-linked financing to protect margins and extend customer relationships.
-
For hospital systems and imaging networks: Adopt a portfolio approach—retain a mix of high-throughput digital systems for volume procedures, and specialized CZT-enabled units for centers of excellence. Negotiate lifecycle service agreements that align incentives around uptime and exam quality.
-
For investors and M&A teams: Seek targets that fill gaps in service networks, bring proprietary detector technologies, or provide access to differentiated clinical algorithms. Pay attention to installed-base service economics as a value driver.
-
For policymakers and payers: Encourage clinical trials that demonstrate comparative effectiveness, and align reimbursement with outcomes that reward diagnostic accuracy, lower downstream costs, and improved throughput.
What the report does not disclose here — and why
This briefing intentionally omits fine-grained geographic or application share tables and specific segment-level dollar figures in order to preserve the full strategic value of the complete report. PW Consulting’s full dataset includes granular regional splits, application-specific demand curves, and vendor-level market share estimates that are essential for transaction diligence, procurement strategy, and product prioritization.
How to use the full report in 2026 planning
-
Scenario workshops: Use the included scenario models to stress-test capital procurement plans under reimbursement shifts and device-substitution scenarios.
-
Vendor selection: Apply the vendor scorecards and technology assessments as a short-listing tool for RFPs and pilot deployments.
-
M&A diligence: Leverage the target-screening and valuation appendix to prioritize acquisition targets and build integration playbooks focused on service expansion.
-
Regulatory strategy: Follow the report’s regulatory navigator to align 510(k) strategies with post-market surveillance requirements and clinical-evidence generation.
Next steps
For executives preparing 2026 capital plans, PW Consulting’s Worldwide SPECT Camera Market report is built to convert market intelligence into executable strategy—balancing clinical, commercial, and regulatory lenses. To access the complete dataset, vendor-level shares, and the procurement-ready appendices that underpin these recommendations, please visit our report page and download the full study.
For detailed analysis of this topic, please visit the official page: Worldwide SPECT Camera Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Palatal Expander Market Poised to Climb from USD 745.5 Million in 2025 to USD 1,290.13 Million by 2032 on an 8.15% CAGR
By pmarketresearch, 2026-08-12
PW Consulting: Worldwide Palatal Expander Market — Strategic Imperatives for 2026
PW Consulting today publishes its definitive market research briefing on the Worldwide Palatal Expander Market. Built from a comprehensive review of historical performance (2020–2025) and forward-looking scenario planning for the 2026–2032 forecast window, the report translates market dynamics into decision-ready recommendations for executives, product teams, clinical partners, and investors preparing strategies for 2026 and beyond.
Mobile Modular Substation for Transportation Market
Why this report matters for 2026 decision cycles
-
An accelerating growth profile. The palatal expander market is expanding at a compound annual growth rate of approximately 8.15% through our forecast horizon, reflecting sustained modernization of orthodontic care pathways and widening clinical indication sets.
Nylon Quick-Disconnect Terminal Market -
Near-term momentum. Using 2025 as our base year, the market size is reported at USD 745.5 Million, with the market crossing the USD 800 Million threshold in 2026 under our base scenario — a practical reminder that material revenue pools and adoption inflection points are imminent for stakeholders who move early.
3D Printing Design Software Market -
Moderate consolidation with meaningful pockets of openness. Market concentration metrics indicate a competitive landscape where leading vendors hold meaningful shares, yet nearly half the market value remains outside the top five players — an environment that rewards clinical innovation, channel sophistication, and attractive partnership models.
-
Regulatory and reimbursement forces are re-shaping adoption. Recent device clearances and regulatory approvals for novel removable and digitally manufactured expanders have materially improved market access in major geographies, while coding and reimbursement pathways remain an active strategic lever for commercial success.
High-level market trajectory (select figures)
-
Base year: 2025 (USD 745.5 Million)
-
Short-term projection: 2026 (USD 806.26 Million)
-
Long-term scale: 2032 (USD 1,290.13 Million)
-
Forecast horizon: 2026–2032, CAGR ~8.15%
Report highlights — what we deliver
-
Robust market-sizing and scenario models: granular bottoms‑up and tops‑down modeling with sensitivity trees that isolate demand drivers (demographics, referral patterns, clinical protocols), supply-side constraints (lab throughput, device lead times), and substitution risks (alternative orthodontic modalities).
-
Actionable go-to-market playbook: channel segmentation, clinic and lab engagement frameworks, pricing playbooks tied to reimbursement pathways, and cross-sell strategies for adjacent orthodontic products.
-
Regulatory and reimbursement matrix: a concise, regionally organized decision map highlighting classification, common coding (orthodontic CDT codes), and market-entry gating items that materially affect time-to-revenue.
-
Competitive intelligence and capability assessment: profiles of incumbents and adjacent entrants, capability heat maps (R&D, manufacturing, digital workflows, clinician training), and an M&A/partnership screen to prioritize targets by strategic fit.
-
Operational playbooks for labs and OEMs: workflows that match traditional fabrication with CAD/CAM and direct 3D printing strategies, quality-management checkpoints (ISO-aligned), and cost-to-serve calculators for digital vs. analog production paths.
-
Commercial readiness assets: executive one-pagers, an interactive Excel demand model, go/no-go investment scorecards, and a prioritized 12–24 month tactical roadmap to accelerate near-term uptake.
Competitive landscape — who is shaping the market
The market is populated by a mix of established orthodontic suppliers, specialized labs, and disruptive digital entrants. Our competitive analysis profiles leaders across product, channel and clinical-service vectors, and assesses three strategic postures: product innovation, channel consolidation, and platform-enabled care.
-
Digital-first entrants are changing the rules. Companies that combine intraoral scanning ecosystems with digitally fabricated appliances have moved palatal expansion beyond traditional screw-and-band models into removable, patient-friendly systems. Notably, a major aligner platform secured additional regulatory clearances and CE certification across markets in 2024–2025, enabling commercial launches in several jurisdictions and creating a pathway for digitally delivered expansion therapies.
-
Traditional manufacturers and labs maintain strong clinical trust. Established suppliers and orthodontic laboratories continue to provide the breadth of fixed expanders, MARPE systems, and bespoke lab services that clinicians rely on for complex cases. Their strengths—clinical relationships, manufacturing quality, and distribution depth—remain strategic assets.
-
Clinical-device convergence is emergent. Implant-supported and surgically assisted expansion approaches continue to mature, requiring suppliers to integrate mechanical engineering expertise with clinical training programs and surgeon/orthodontist co-management models.
Recent catalyst events and their strategic implications
-
Regulatory approvals for digitally printed removable expanders lower adoption friction. The cascade of approvals and CE marking for a leading removable expander system in 2024–2025 expands addressable patient cohorts and reduces clinic chair-time for activation and adjustments.
-
Market availability in APAC and EMEA unlocks scale for digital solutions. Staggered geographic launches create staged revenue ramps and localized competitive responses—an ideal environment for selective partnerships and territory-focused pricing strategies.
-
Reimbursement and coding remain a decisive variable. Orthodontic treatments are commonly billed under existing CDT codes; the way payers interpret appliance-versus-service, bundled treatment stages, and age-based eligibility will materially affect payer mix and ASP realization.
Strategic implications for 2026 planning horizons
-
Prioritize digital workflows that reduce clinic operational friction. Investments in scanner-to-manufacturing integration and clinician training yield differentiated value — particularly for practitioners seeking chair-time efficiencies and predictable treatment outcomes.
-
Design reimbursement-first commercial models. Companies that align product design, clinical value messaging, and payer engagement stand to accelerate adoption. Translate clinical outcomes into coding and claims evidence early in the launch sequence.
-
Adopt a two-speed partnership strategy. Fast-follower alliances with regional lab networks accelerate local scale; deeper strategic partnerships with digital platforms secure product integration and recurring revenue streams.
-
Build modular product portfolios to serve both pediatric and adult cases. Adult indications, especially when combined with surgical adjuncts (e.g., miniscrew-assisted approaches), require enhanced mechanical specifications and cross-specialty clinical pathways.
-
Target M&A and licensing as a near-term route to capability acquisition. Given the moderate concentration levels, tactical acquisitions of lab capacity, niche device IP, or digital enablement platforms can be higher-velocity alternatives to organic build.
How PW Consulting’s report accelerates decision-making
We designed this briefing to be a practical tool for 2026 planning cycles. The deliverables include validated market sizing, price and reimbursement impact models, a prioritized list of markets and clinical segments by strategic attractiveness, and playbooks for commercialization, regulatory clearance, and lab partnership deployment. Each recommendation is tied to an implementation timeline, resource estimate, and downside risk mitigation plan.
What we intentionally withhold in this briefing (and why)
In keeping with the “trailer” approach of this release, we present high-confidence market-level facts and strategic insights while withholding the granular segmentation tables and region-by-application dollar breakdowns that underpin our models. Those core datasets — including detailed regional, product-type and end-user splits — are available exclusively in the full report and accompanying financial model. The intent is simple: senior leaders need crisp intelligence to prioritize action in 2026, and we provide enough directional clarity here while reserving the full dataset for decision execution by subscribing organizations.
Who should read the full report
-
CEOs, business-unit heads, and corporate development teams at OEMs and dental-tech platforms evaluating new product lines or geographic expansion.
-
Heads of product, R&D, and clinical affairs planning launches or regulatory submissions for next‑generation expanders.
-
Investor teams and PE sponsors assessing M&A targets or roll-up strategies in orthodontic devices and laboratory networks.
-
Large dental laboratory groups and regional distributors devising capability upgrades and partnership roadmaps.
Next steps
For stakeholders preparing budgets, product roadmaps, or M&A pipelines for 2026, this report offers a compressive, executable view of market opportunity and risk. To access the full dataset, company profiles, market splits and our interactive financial model, please visit the PW Consulting report page or contact our research team for a briefing tailored to your strategic questions.
PW Consulting’s Worldwide Palatal Expander Market report translates technical innovation and regulatory momentum into concrete commercial tactics — enabling market leaders and new entrants alike to convert growing demand into sustainable, profitable presence in a market poised for continued expansion.
For detailed analysis of this topic, please visit the official page: Worldwide Palatal Expander Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Picrorhiza Extract Market to Grow at a 6.42% CAGR Through 2032
By pmarketresearch, 2026-08-12
Worldwide Picrorhiza Extract Market: Strategic Signals for 2026 Decision-Making
As global demand for high-value botanical extracts continues to intersect with rising interest in conservation-conscious sourcing, Picrorhiza kurroa (commonly referred to as Kutki) has moved from a niche herbal ingredient to a strategic raw material for nutraceutical, pharmaceutical and personal-care value chains. PW Consulting’s latest market study—anchored on a 2025 base year and projecting across 2026–2032—synthesizes macro trajectories, supply-side constraints and actionable pathways that procurement, R&D and M&A teams must weigh when setting 2026 priorities.
Worldwide Sports Agency Service Market
Why this report matters for 2026
-
Clear macro momentum: The Picrorhiza extract market is at a definable inflection point. Our analysis places the global market at approximately USD 48.65 Million in 2025 and forecasts continued expansion through 2032, with a compound annual growth rate (CAGR) of roughly 6.42% across the forecast window. By 2032 the market is projected to be materially larger, reflecting both rising product adoption and new formulation applications.
Worldwide OLED Equipment Market -
Supply-side fragility meets demand-side innovation: Longstanding supply constraints—rooted in high-altitude, wild-harvested sourcing and regulatory protections—create a structural premium on traceable, certified supply. At the same time, new scientific findings and evolving end-use formulations are expanding the addressable market beyond traditional segments.
Worldwide Fire Retardant Additives Market -
Decision leverage: For mid-market and enterprise buyers alike, 2026 will be a year to convert strategy into contracts: securing diversified supply agreements, prioritizing cultivated and certified material, and fast-tracking product differentiation that leverages standardized extract formats and novel synbiotic combinations.
What the report delivers (practical, decision-ready content)
-
Robust market sizing and scenario modelling: Our base-year valuation (2025) and detailed 2026–2032 forecast—anchored in primary interviews, trade-tracking and on-the-ground supplier intelligence—offer a range of scenarios to stress-test procurement and commercialization plans.
-
Go-to-market playbooks for buyers and suppliers: Tactical procurement templates, contract clauses for long-term supply, and a supplier-evaluation scorecard that balances price, traceability and conservation commitments.
-
Value-chain mapping and cost-driver analysis: From Himalayan collection systems through extraction, standardization and formulation, the report isolates the levers that matter for margin expansion and supply assurance.
-
Regulatory and ESG risk matrix: Practical guidance on CITES implications, national export constraints, and certification pathways (organic, fair-trade, traceability) that are necessary to de‑risk market entry and premium claim substantiation.
-
Innovation and product pipeline intelligence: Assessment of formulation trends (standardized extracts, powders, liquid extracts) and emerging applications—plus an evidence brief summarizing the latest scientific developments relevant to product claims and positioning.
-
Competitor and supplier dossiers: Profiles and strategic positioning of leading producers and exporters, including acquisition targets, capability gaps and potential partnership archetypes.
Competitive landscape — what to know about suppliers and strategic partners
The market is characterized by a dispersed supplier base with a number of specialized producers concentrated in South Asia, and a presence of manufacturers in East Asia. Key industry participants include:
-
Botanic Healthcare (India) — positioned as a bulk manufacturer and exporter of premium organic Picrorhiza root extract with export-oriented compliance and established nutraceutical customer relationships. Their strength is scale in organic-certified supply and export infrastructure.
-
Herbal Creations (India) — a consistent B2B supplier focused on process consistency; attractive for brands seeking dependable lot-to-lot quality.
-
BKHerb (Bolise Co., Ltd.) (China) — offers regional manufacturing capability and can be an alternative industrial player for formulators prioritizing domestic East Asian supply chains.
-
SA Herbal Bioactives (India) — notable for positioning Picrorhiza as an income-generating forest product in Nepalese supply chains; relevant to impact investors and sustainability programs.
-
Kshipra Biotech, Suhani Agro Industries, Raj Food and Pharma, and Anjum Extraction (India) — represent a set of mid-tier manufacturers and packagers who compete on purity, packaging formats and lead times.
For 2026 strategy, the report breaks down how to segment suppliers by capability (organic certification, standardized-extract manufacturing, contract-development readiness), and recommends negotiation tactics depending on whether you prioritize cost, traceability, or innovation partnership.
Regulatory and sourcing realities that will shape 2026 decisions
-
International trade regulation: Picrorhiza kurroa has been subject to international controls designed to limit overharvesting. Buyers must factor CITES listings and national restrictions into sourcing timelines and contractual terms, including clauses for force majeure, export permit timelines and substitution protocols.
-
Endangered status and cultivation pressure: Scientific and field research—particularly recent cultivation studies—underscore a transition opportunity: organized cultivation to replace or supplement wild-harvest. For buyers, investing in cultivation partnerships and contract farming is a hedge against supply shocks and reputational risk.
-
Raw material tightness: Historical scarcity in wild material has generated persistent imbalances between demand and supply. This dynamic increases exposure to price volatility and delivery risk unless proactively managed through diversified sourcing and inventory policy adjustments.
Scientific and product innovation — emerging catalysts for value creation
Two recent developments are particularly strategic for product teams:
-
Synbiotic potential (Jan 2026): A research consortium has published preprint data indicating Picrorhiza kurroa may act synergistically with probiotic strains (e.g., Lactobacillus fermentum) to create differentiated synbiotic formulations. This opens a route for claims-driven launches in gut-health and integrative wellness categories, where premium positioning can offset raw-material cost inflation.
-
Cultivation research (2025): Studies on organized cultivation in Himalayan regions create a playbook for scale-up and conservation-aligned sourcing. Buyers that finance or enter contract-farming agreements early can shape cultivar selection, agronomy practices and traceability systems to lock-in quality advantages.
Strategic actions for 2026 — a prioritized checklist
-
Operationalize supply diversification: Establish triaged supplier tiers (strategic, tactical, contingency) and conclude at least one multi-year agreement with a cultivated-source supplier before Q3 2026.
-
Invest in traceability and certification: Allocate budget to support supplier upgrades (e.g., organic, traceable lot systems) and align purchasing terms to certification milestones rather than price alone.
-
Pursue R&D partnerships: Pilot synbiotic formulations leveraging recent scientific evidence; fast-follower brands should accelerate lab validation and claim substantiation in 2026.
-
Consider upstream investments: For firms with scale, evaluate minority equity or joint-venture investments in cultivation projects—this secures raw material, creates margin capture, and delivers ESG credentials.
-
Refine inventory and pricing playbooks: Increase safety stock where logistics risk is measurable, and adopt dynamic pricing contracts (e.g., price bands tied to certified supply share) to protect margins without disincentivizing supplier investments in sustainability.
-
Audit and compliance acceleration: Fast-track supplier audits and CITES/export-compliance checks as part of onboarding; regulatory timelines are often the critical path for launch calendars.
What this means for different stakeholders
-
Procurement leaders: Treat Picrorhiza as a strategic raw material. Shift from spot purchases to strategic partnerships and structured procurement instruments that include quality, traceability and conservation KPIs.
-
Product and R&D teams: Prioritize formulations that leverage standardized extracts and the synbiotic opportunity; engage regulatory early to lock in permissible claim frameworks.
-
Investors and corporate development: Early-stage investments in cultivation and processing assets can be accretive to supply certainty and margin; M&A opportunities exist among mid-tier processors with export capabilities and certification portfolios.
-
ESG and sustainability teams: Align sourcing policies with conservation goals and community-benefit frameworks to reduce reputational risk and support long-term supply resilience.
Why PW Consulting’s report is the right tool for 2026 planning
Our study marries quantitative forecasting (base-year market sizing and 2026–2032 scenarios) with qualitative field intelligence—supplier audits, policy risk mapping and primary interviews—so executives can move from strategic intent to operational commitments in 2026. The analysis is structured to support three immediate decision pathways: secure supply, accelerate innovation, or invest upstream. Which pathway (or combination) a company selects will determine both risk exposure and margin opportunity over the next three years.
Limited preview — full intelligence available on request
This article highlights strategic themes and practical levers. To preserve the competitive value of our granular segmentation (regional and application splits, supplier-by-capability scoring, and pricing-band matrices), full datasets and cell-level forecasts are made available in the report package. Executives and procurement teams evaluating 2026 programs should consult the complete report for confidential annexes, scenario workbooks and supplier scorecards.
To obtain the complete Worldwide Picrorhiza Extract Market report, including downloadable datasets and the supplier diligence annex, visit PW Consulting’s research portal or contact our insights team. The right combination of sourcing agility, certification investment and product innovation in 2026 will determine who captures the premium growth ahead—this report provides the operational roadmap to act.
For detailed analysis of this topic, please visit the official page: Worldwide Picrorhiza Extract Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide During Production Inspection (DPI) Market to Hit USD 845.05 Million by 2032 on a 6.45% CAGR
By pmarketresearch, 2026-08-12
Worldwide During Production Inspection (DPI) Market: Strategic Imperatives for 2026
PW Consulting’s latest market research on the Worldwide During Production Inspection (DPI) market delivers a focused, operationally grounded view designed to inform boardroom and procurement decisions in 2026. Our analysis shows a market that has accelerated from roughly USD 395 million in 2020 to approximately USD 546 million in 2025 and is forecast to expand to about USD 845 million by 2032, reflecting a compound annual growth rate of 6.45% over the forecast horizon. These headline figures underscore a durable, mid-single-digit growth opportunity underpinned by regulatory tightening, supply-chain risk management, and rapid technology adoption — but they also mask critical differentiation between service models, verticals and geographies. This release summarizes the strategic takeaways and describes the hands-on tools embedded in the full report (with detailed segmentation and datasets available via our website).
Containerized Mobile Renewable Energy Unit Market
Why 2026 Is a Strategic Inflection Point
Three forces converge in 2026 to make DPI an operational priority rather than a cost center: (1) heightened regulatory scrutiny that elevates liability and product surveillance during manufacturing; (2) commercial pressure to shorten time-to-market while maintaining quality; and (3) rapid adoption of digital remote monitoring and analytics that change how inspection services are delivered and priced.
Robotic Agent Market
- Regulatory drivers: International standards governing inspection body competence (e.g., ISO/IEC 17020) and regional market surveillance frameworks are increasingly explicit about inspecting during production. Compliance programs are becoming prerequisites to market entry in multiple jurisdictions.
- Technology disruption: Remote digital monitoring is shifting the economics of DPI. Adoption accelerates cost-efficient coverage of distributed supplier bases, but it also requires new controls, cybersecurity considerations, and data governance.
- Labor and automation: The median annual wage for quality control inspectors and the projected employment shifts driven by automation should prompt firms to re-skill and reconfigure inspection staffing as part of broader productivity investments.
Market Trajectory and Capital Allocation Implications
The DPI market’s compound annual growth rate of 6.45% through the forecast period suggests steady expansion, driven by both legacy on-site verification and a growing layer of remote and hybrid services. For 2026 capital allocation, executives should treat DPI as a strategic enabler of resilient supply chains: investments that reduce recall risk, accelerate supplier onboarding, and protect brand value.
Intelligent Driver Testing and Training System Market
- Investment focus: Prioritize capex and opex that create modular inspection capabilities — for example, hybrid inspection teams, remote monitoring platforms, and integrated lab-to-inspection workflows.
- M&A and partnerships: Expect mid-market consolidation opportunities where global reach, digital platforms, or specialized vertical expertise can be stitched into client-facing bundles.
- Service packaging: Shift from time-and-material inspection contracts to outcome-based and subscription models tied to quality KPIs and reduced time-to-release.
What the Report Contains: Practical, Actionable Deliverables
PW Consulting’s DPI report is designed as an operator’s toolkit for 2026. The full publication contains:
- Methodologies and data: Transparent forecasting approach, model assumptions, sensitivity tests and downloadable time-series for the overall market.
- Operational playbooks: Standardized inspection protocols, decision trees for choosing on-site vs. remote inspections, templated RFPs and SOWs, and contractual clauses to manage workmanship, data ownership and liability.
- KPI and benchmarking frameworks: Benchmarks for inspection pass/fail rates, defect distributions, cycle-time to corrective action and customer holdback metrics tailored to industry verticals.
- Digital adoption roadmap: A phased implementation plan for remote monitoring, including vendor selection criteria, pilot KPIs, integration checklists for ERP/QMS systems and expected ROI timelines.
- Procurement and supplier selection: Due-diligence checklists and scorecards that align inspection scope with supplier risk tiers and regulatory obligations.
- Scenario playbooks: Stress-tested action plans for regulatory shifts, factory closures, or rapid SKU proliferation — including contingency staffing, rapid audit templates, and escalation workflows.
These assets are intentionally operational: procurement teams, quality directors and compliance officers can extract immediate, tactical change items without needing to rework our models.
Competitive Landscape: Who Matters and How They Compete
The DPI market is characterized by a mix of large, diversified assurance providers and focused specialists. Market concentration is moderate: our concentration analysis shows that the top three providers account for a meaningful but not dominant share, and the top five amplify that position — an environment that supports both scale plays and specialist entrants.
- SGS (Geneva): A global leader with deep on-site verification capability across electronics, automotive and consumer goods. Their strength is international footprint and cross-border logistics for large-scale retail and industrial programs.
- Bureau Veritas (Neuilly‑sur‑Seine): Known for integrating DPI within broader supplier audit and production monitoring suites, making them attractive for enterprises seeking single‑vendor assurance stacks.
- Intertek (London): Focuses on real-time quality assurance for hardgoods and electrical products; successful at packaging testing and DPI into tight product release timelines.
- TÜV Rheinland (Cologne) & TÜV SÜD (Munich): European specialists emphasizing industrial, automotive and renewables. Their competitive edge is technical depth and process monitoring expertise.
- DNV (Bærum) & LRQA (London): Bring sector-specific assurance for maritime, oil & gas and energy projects, often coupling DPI with certification and lifecycle assurance.
- DEKRA (Stuttgart), Eurofins (Luxembourg City) & UL Solutions (Northbrook): Offer complementary capabilities — DEKRA with vehicle/industrial focus, Eurofins with integrated testing for life sciences and consumer health, UL with safety compliance and appliance testing.
- Kiwa (Rijswijk), Cotecna (Geneva), Applus+ (Barcelona): Regional specialists that combine local standards expertise with targeted laboratory networks and trade facilitation services.
For buyers, this landscape implies three practical behaviors: (1) use competition to drive bundled pricing where labs + DPI deliver tangible cycle-time improvements; (2) seek regional partners with local regulatory expertise; and (3) evaluate digital capability as a primary procurement criterion, not an optional add‑on.
Strategic Playbook for 2026 Decision-Makers
We advise a prioritized, two-year program for firms that wish to convert DPI from a compliance checkbox into a competitive advantage:
- Adopt a hybrid delivery model: Combine targeted on-site inspections with continuous remote monitoring. Start with a small cohort of high-risk suppliers and scale by ROI.
- Embed regulatory readiness: Update supplier contracts and SOPs to reflect ISO/IEC 17020 competence criteria and applicable market surveillance rules. Build regulatory triggers into your supplier tiering logic.
- Reskill quality teams: Reallocate headcount from routine inspection tasks to analytics, exception management and supplier engineering support. Use automation to redeploy inspectors toward higher-value verification.
- Invest in data interoperability: Prioritize platforms that integrate inspection reports with ERP, PLM and supplier portals to reduce reconciliation lag and accelerate root-cause workflows.
- Pursue strategic partnerships: Where internal build is slow, use joint ventures or white‑label arrangements with established DPI providers to accelerate geographic or vertical expansion.
- Revise commercial models: Experiment with outcome-based pricing tied to defect rates, time-to-corrective-action and reduced rework costs.
Risk Factors and Contingency Measures
Leaders must evaluate three clusters of risk as they scale DPI capability:
- Regulatory volatility: Enforcement scope and technical standards evolve; maintain a regulatory horizon-scanning function and escalate changes into contract clauses.
- Technology adoption lag: Remote monitoring reduces cost but increases reliance on data integrity. Pilot cybersecurity and data governance early in the deployment cycle.
- Workforce transition risk: Automation reduces routine inspector roles; institute retraining programs and maintain knowledge transfer protocols to preserve institutional expertise.
How PW Consulting Can Accelerate Your 2026 Outcomes
PW Consulting supports executive teams with tailored services that move beyond diagnostics into implementation. Our offering includes:
- Due diligence for DPI-related M&A and partnerships, including commercial, operational and technology assessments.
- Vendor selection and contracting support that embeds regulatory and data-governance requirements.
- Pilot design and scaled roll-out roadmaps for hybrid inspection programs, with KPI dashboards and measurable cost/quality targets.
- Regulatory gap analysis against ISO/IEC 17020 and major market surveillance frameworks, plus remediation roadmaps.
- Workforce transformation programs focused on inspector upskilling, productivity metrics and transition incentives.
Each engagement is calibrated to the commercial levers most material for the client — whether margin protection, speed-to-market or risk mitigation.
Closing: What You Can Do Next
DPI is a growing, structurally important market segment. Its forecast trajectory points to continued investment, but the shape of value capture will differ markedly between scale-driven service providers and niche specialists. To translate market growth into competitive advantage in 2026, executives must move from ad-hoc inspection commissioning to integrated assurance strategies that combine regulatory readiness, digital-enabled monitoring and supplier engineering partnerships.
PW Consulting’s full Worldwide DPI Market report provides the detailed segmentation, country-level overlays, and downloadable datasets to operationalize these recommendations. The document also includes proprietary benchmarking tables and vendor scorecards to expedite procurement decisions — an essential next step for teams that want the full, implementable intelligence behind this executive summary.
For detailed analysis of this topic, please visit the official page: Worldwide During Production Inspection (DPI) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com